Buying Logistics
Can you buy a sauna with HSA or FSA money? Sometimes, with the right paperwork
A sauna can qualify for HSA or FSA money only with a Letter of Medical Necessity. We set out the IRS rules and the paperwork in the order it has to happen.
By Adam Bognar, Editor

A sauna can be an HSA or FSA expense only with a Letter of Medical Necessity from a licensed provider tying it to a diagnosed condition. We read the IRS rules and lay out each step in order. The IRS has always let expenses qualify as medical care when their primary purpose is to treat or mitigate a diagnosed condition. Benefits administrators call a sauna a dual-purpose item, so it needs the letter to cross from wellness purchase to medical expense. Done in order, that's a 20–40% effective discount depending on your tax bracket, and a paperwork mistake means a denied claim or an audit headache.
The IRS rule comes down to primary purpose
IRS Publication 502 defines medical expenses as costs for the diagnosis, cure, mitigation, treatment or prevention of disease. That list never mentions saunas, either to include them or to exclude them. Primary purpose decides the question, and general health and relaxation don't qualify. Heat therapy that a clinician recommends for a specific condition can qualify, whether that's chronic pain, cardiovascular rehabilitation, arthritis or certain skin conditions. You have to document that distinction, and the Letter of Medical Necessity is how you do it.
Get the Letter of Medical Necessity before you buy
An LMN is a short letter from a licensed provider. It states your diagnosis and the treatment it recommends (regular sauna use), then explains why that treatment addresses your condition. The order matters, so get the letter before you buy.
Services like Truemed have made this nearly frictionless. You complete an async health evaluation, and if a provider determines heat therapy is appropriate for you, an LMN arrives by email within days. Several sauna retailers have Truemed integrated directly at checkout, so the evaluation happens as part of the purchase.
You can pay at checkout or claim a reimbursement
The cleanest path is a merchant that takes HSA/FSA payment directly through Truemed or a similar service. You check out with your HSA card and the LMN is attached automatically. Otherwise, pay out of pocket and submit the receipt plus the LMN to your plan administrator for reimbursement.
Administrators differ. Some reimburse saunas routinely with an LMN. Others cap the amount, and a few refuse dual-purpose items entirely. A five-minute call to yours before you order saves the most common unpleasant surprise.
Where to buy


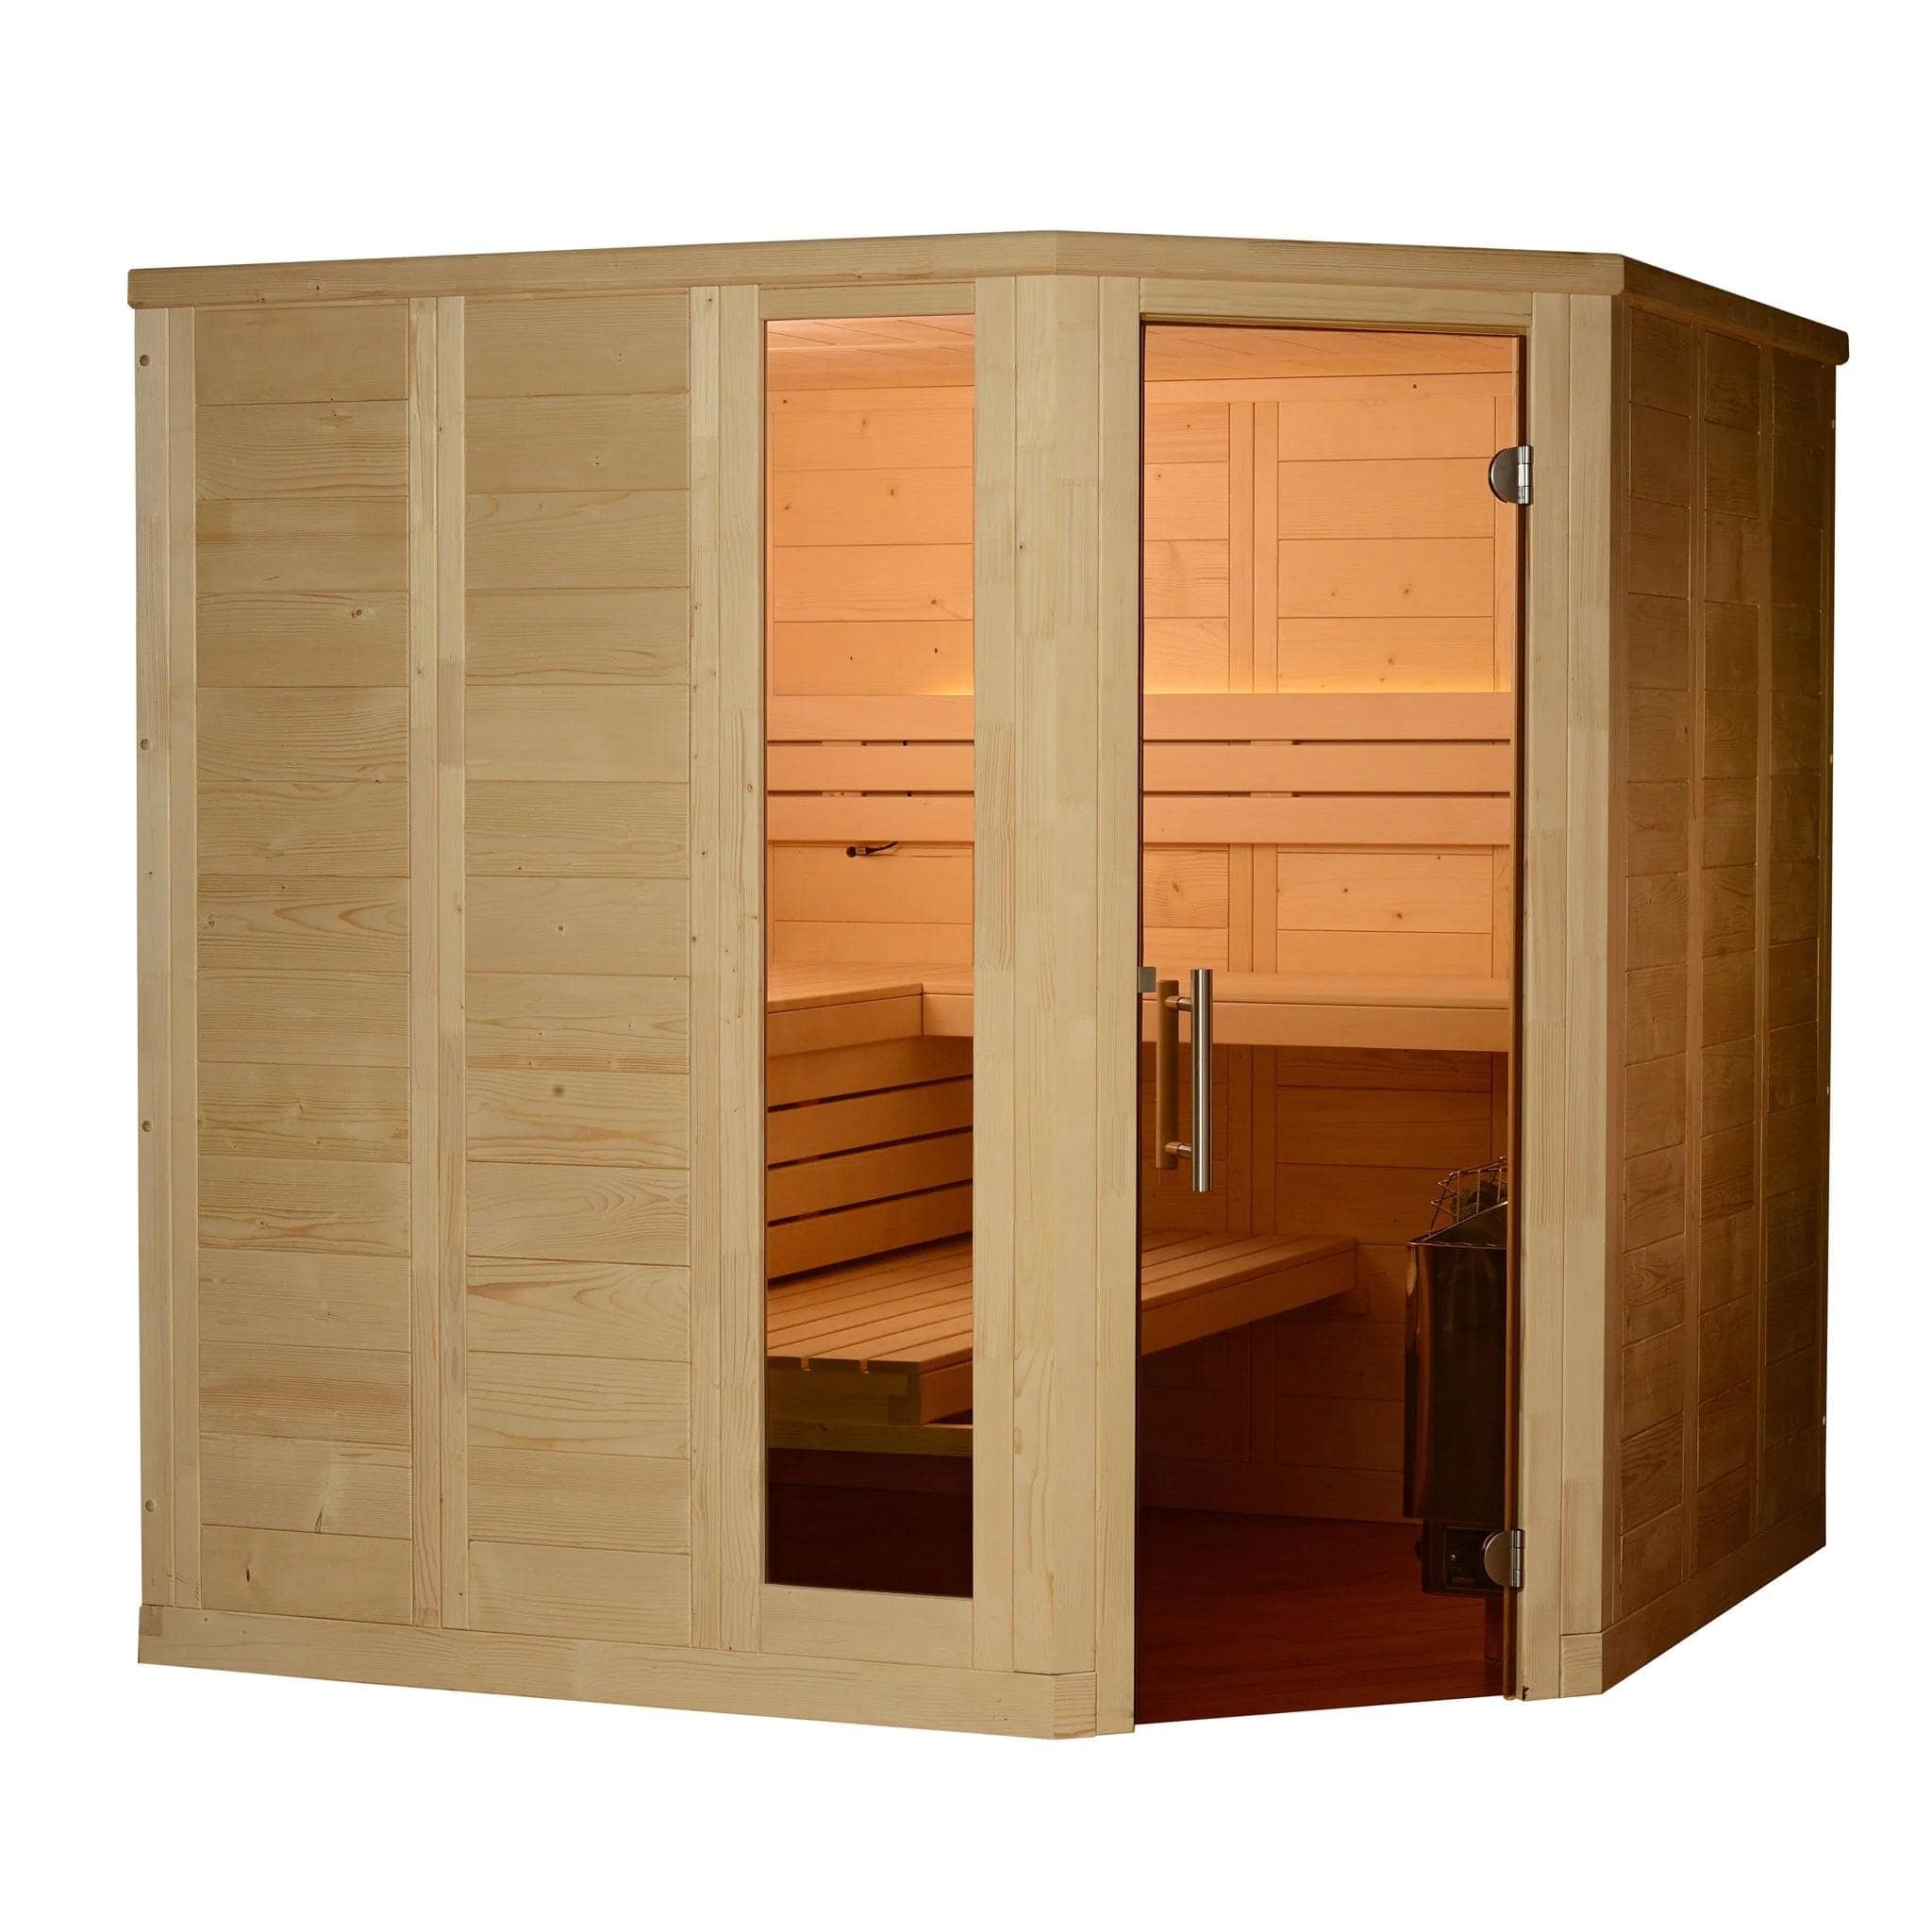
Almost Heaven Saunas Indoor Saunas
Almost Heaven Patterson 6-Person Indoor Sauna


Barrel Outdoor Sauna - 6 Person. Redwood Outdoors photography.
See the specifications and priceBig-ticket saunas usually go through an HSA
We ran the numbers at a 30% combined marginal rate. On a $6,000 barrel sauna, paying with pre-tax dollars keeps roughly $1,800 you'd otherwise send to the IRS. The saving on a $700 infrared blanket comes to about $200.
An FSA brings the use-it-or-lose-it deadline and a lower contribution ceiling. Big-ticket saunas usually route through an HSA instead, where funds roll over and the balance can cover the purchase.
Where to buy

HigherDOSE Sauna Blankets & Portables
HigherDOSE Infrared Sauna Blanket
“This blanket brings heat therapy to renters and stows under a bed afterward.”

Therasage Sauna Blankets & Portables
Thera360 PLUS Personal Sauna (Black)
Avoid these four paperwork mistakes
Nearly every horror story traces back to one of four mistakes. Buy first and seek the letter afterward, and administrators read it as retroactive justification. A letter from a provider who never evaluated you is worthless under audit.
Don't assume approval transfers, either. An LMN documents eligibility, but your administrator makes the call, and the IRS can still disagree at audit time, where the burden of proof is yours.
Then there's the capital-expense rule. A permanently installed sauna that increases your home's value only qualifies for the cost above that value increase, and a freestanding barrel or portable unit sidesteps that entirely.
Keep the LMN and receipt for seven years, with the claim paperwork. We review saunas, so ask a CPA about your taxes when real money is at stake.
Common questions
- Are saunas automatically HSA/FSA eligible?
- No. A sauna is a dual-purpose item, so it requires a Letter of Medical Necessity from a licensed provider tying it to a diagnosed condition. Without an LMN, it's a general-wellness purchase and doesn't qualify.
- What conditions typically support a sauna LMN?
- Providers commonly write sauna LMNs for chronic musculoskeletal pain, arthritis, cardiovascular risk management and hypertension, plus some skin and stress-related conditions. Heat therapy has a plausible therapeutic role in each. The provider's judgment decides, and there's no fixed list.
- Do sauna blankets and portable saunas qualify too?
- Sauna blankets and portable saunas can qualify under the same rules. An LMN converts the purchase into a medical expense regardless of form factor or price. Portable units avoid the capital-expense complication that permanently installed saunas can trigger.
- Can I use HSA money for the electrician or installation?
- Possibly, if the sauna itself qualifies. IRS Publication 502 treats special equipment installed in a home for medical care as a capital expense, so the installation and the required electrical work count toward that cost, minus any increase in your home's value. Operation and upkeep costs can also qualify when medical care is the main reason for them.
Sources
- 1.Publication 502: Medical and Dental Expenses. Internal Revenue Service, 2025.
- 2.Association Between Sauna Bathing and Fatal Cardiovascular and All-Cause Mortality Events. JAMA Internal Medicine, 2015.
- 3.Cardiovascular and Other Health Benefits of Sauna Bathing: A Review of the Evidence. Mayo Clinic Proceedings, 2018.
We review from makers’ documentation, owner reports and published research. How we choose products and write reviews.